JOB COST REVIEW
Job Cost Overruns: Explain the Difference with Photos, Hours and Notes
The job is complete, but its recorded delivery cost is higher than the estimate. Was the original work underestimated? Did the customer add work? Did the crew wait for access? Or has the same purchase been entered twice?
“It took longer” does not answer those questions. A useful review connects the original scope, recorded labor, material costs and supporting field evidence.
Start with one rule: explain the difference before deciding what to change. An internal cost increase, a customer-approved scope change and an additional customer charge are different things.
Fieldnox is our product. This guide uses a fictional service job and a copyable review template. The worksheet is a manual management record, not a complete accounting system or a Fieldnox costing feature.
Quick takeaway: Compare actual job cost with the original estimate, separate approved added work, and connect every remaining difference to a record.
Preserve the original estimate
Keep the original estimate, its version and the work it covered. If the scope changes, record that separately rather than replacing the starting point.
For each cost category, compare like with like:
- Labor: person-hours and the internal hourly cost used for each entry.
- Materials: the cost allocated to materials actually used on this job, with returns or credits handled consistently.
- Other included costs: clearly identified items such as parking or equipment hire.
State the currency and what is excluded. If the estimate excludes company overhead but the actual includes it, the difference cannot be interpreted as a straightforward delivery overrun.
An employee's internal hourly cost is also different from the hourly price charged to the customer. Apply the same documented cost basis to the estimate and actual, or identify a rate change separately.
Use three records together
Scroll the table horizontally on smaller screens.
| Record | What it helps establish | What it cannot establish alone |
|---|---|---|
| Photos with references and captions | Visible condition, location and stages of work | Exact labor duration, purchase cost or customer approval |
| Time entries | Who recorded time, on which task, and for how long | Why all extra time was necessary or whether it is billable |
| Task notes, approvals and cost records | Work performed, changes, interruptions and amounts supported by source records | That every claim is correct without review |
A useful note says what happened, when, to which work area and what action followed. Attribute statements where needed: “Site contact advised access would be available at 09:15” is different from an independently verified cause of delay.
For photos, use the before-and-after reporting guide to keep the location, view and caption connected to the work.
Example: explain a job cost overrun without hiding added scope
The following figures are invented for training. All amounts are in US dollars (USD). They are not market rates, a customer result or a recommended allowance for this work.
A small maintenance company plans to refresh the painted finish on two interior doors, D-01 and D-02, at a commercial site. Its original internal job cost budget is:
Scroll the table horizontally on smaller screens.
| Cost category | Original budget | Recorded actual | Difference |
|---|---|---|---|
| Labor at $45.00 per person-hour | 4.0 hours × $45.00 = $180.00 | 6.5 hours × $45.00 = $292.50 | +$112.50 |
| Materials allocated to the job | $80.00 | $110.00 | +$30.00 |
| Parking | $20.00 | $20.00 | $0.00 |
| Total recorded job cost | $280.00 | $422.50 | +$142.50 |
These totals exclude company overhead, taxes and revenue. They do not establish full job profitability or an amount owed by the customer.
Two workers each record 3.25 hours, giving 6.5 person-hours. This is not a 6.5-hour visit: their recorded time overlaps. The example includes their waiting time in internal labor cost under the company's stated costing policy; it makes no assumption about customer billing.
Build the explanation from the entries
The team reviews time entries, task notes, material allocation and change record CHG-01:
Scroll the table horizontally on smaller screens.
| Difference from original budget | Supporting record | Internal cost effect |
|---|---|---|
| 0.5 extra person-hours on original scope | Original-scope time entries total 4.5 hours; notes describe additional surface preparation, with photo P02 showing the visible condition | +$22.50 |
| 1.5 person-hours for an added third door, D-03 | Separate task entries and CHG-01, recording agreed scope and price before the added work | +$67.50 |
| 0.5 person-hours waiting for access | Separate, non-duplicated allocations of 0.25 hours, one for each worker; access note and contact time recorded | +$22.50 |
| Materials allocated to the added door | Material issue and cost record linked to CHG-01 | +$30.00 |
| Total explained difference | Each cost allocated once | +$142.50 |
The original-scope work, added work and waiting allocations total 4.5 + 1.5 + 0.5 = 6.5 person-hours. They are separate allocations; waiting is not also counted inside the work entries.
A worked photo caption and access note
For this fictional visit, the reviewer can connect two specific entries:
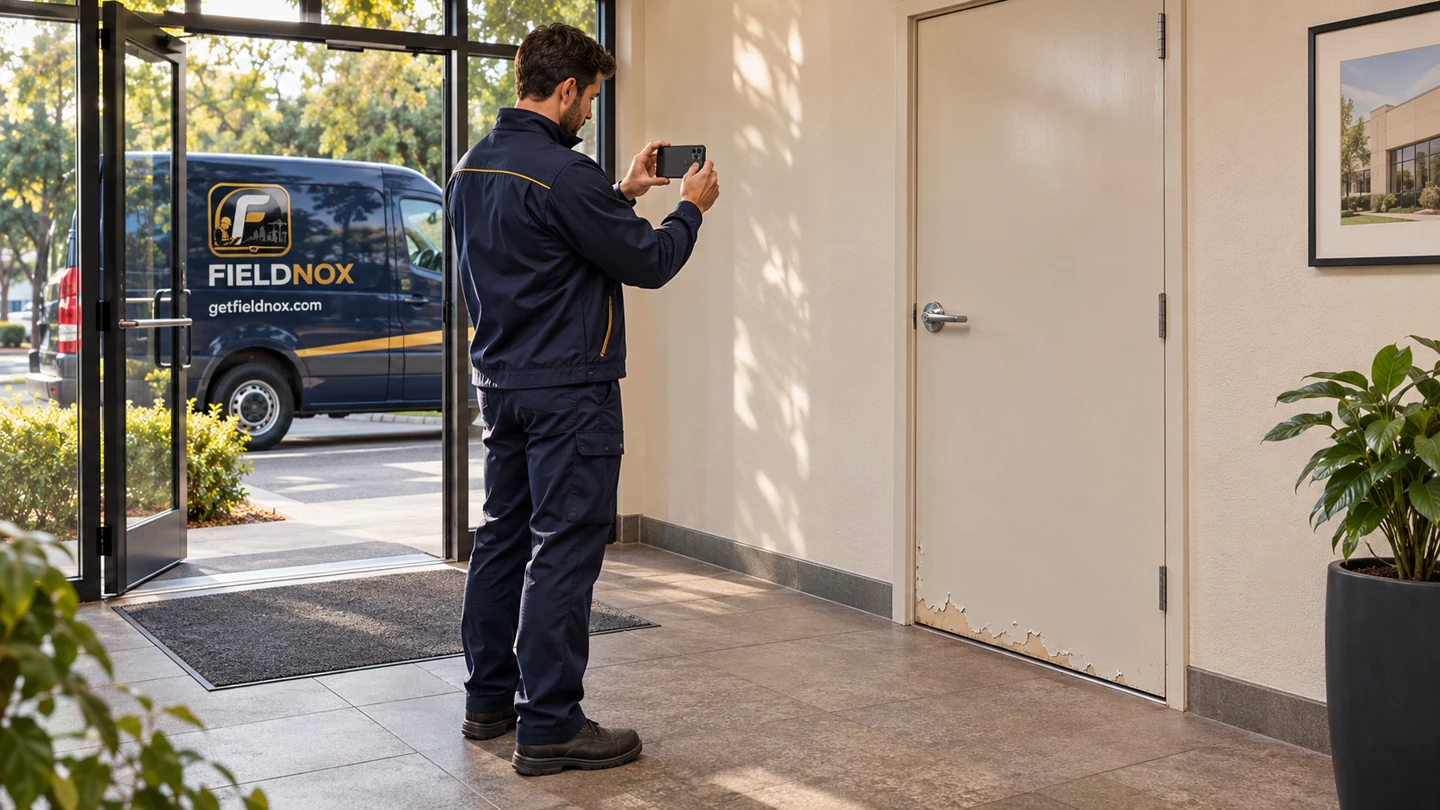
Photo P02 caption: “Job COST-214, door D-02, October 20, 2026, 09:20 local time. Before additional preparation: visible flaking finish at the lower edge. This image records the accessible surface condition; it does not measure preparation time or authorize extra charges.”
Access note: “October 20, 2026, 09:00–09:15 local time. Both workers waited outside the agreed work area. Site contact reached at 09:02; access provided at 09:15. Each worker recorded 0.25 hours against waiting, separately from productive task entries.”
Link P02 to the original-scope task note and time entries. Link the access note to the waiting entries. The records support different parts of the explanation; neither creates a billing entitlement.
The photo helps explain the visible surface condition. The time entries establish the recorded duration. The reviewer still needs to assess whether the explanation is supported; an image does not prove that precisely half an hour was caused by that condition.
Keep both budget views
The added scope has an internal budget allowance of $97.50, recorded before that work: $67.50 labor plus $30.00 materials. This is an internal cost allowance, not the customer's agreed price.
For review, keep these figures visible:
- Original job cost budget: $280.00.
- Added-scope internal allowance: $97.50.
- Revised job cost budget: $377.50.
- Recorded actual job cost: $422.50.
- Difference against revised budget: $45.00.
The job is $142.50 above the original budget, but $97.50 relates to separately recorded added scope. The remaining $45.00 relates to the original-scope estimating gap and waiting time.
Neither view should erase the other. Preserve the original baseline and the change history so that the next estimate can be reviewed honestly.
Resolve missing evidence without inventing a reason
If the time entry says only “extra work,” ask which task changed. If a purchase covers several jobs, identify the allocation rather than charging its whole cost to each job. If an approval reference is missing, mark it as unresolved.
Check for these errors before accepting the explanation:
- Two workers' overlapping time mistaken for elapsed visit time.
- Waiting included in both a task entry and a separate delay entry.
- The same material counted as both a line-item cost and a receipt expense.
- Purchased quantities treated as used quantities without handling unused stock or returns.
- Different cost bases, currencies or time units compared without adjustment.
- A revised estimate overwriting the original baseline.
Use “unexplained difference” for an amount that cannot yet be supported. Assign the missing-information request to someone and give it a target date. A plausible story is not a completed review.
Keep the cost review internal
The internal review may contain employee cost rates, purchase costs, supplier records, rework discussions and pricing decisions. Restrict it to people who need that information.
The customer report should describe the agreed work, relevant evidence, checks actually performed and remaining actions. For the fictional job, a brief entry could say:
“The agreed finish-refresh work on doors D-01 and D-02 was completed. Door D-03 was added under change reference CHG-01. Photo P02 records the visible condition of D-02 before additional preparation.”
Use that wording only when those facts are supported. A customer signature should state what was acknowledged; it does not automatically approve every internal cost or an additional charge.
Keep commercial decisions in their approved process. The completed-job handover guide explains why field completion and invoice readiness need separate review. Use the field service report template for the customer-facing job record.
Copyable job cost difference review
Job / site / review date:
Currency / included cost basis / exclusions:
Original scope / estimate version:
Original job cost budget:
Approved changes / references / internal allowances:
Revised job cost budget:
Actual labor: worker / task / person-hours / internal rate / source:
Actual materials: used quantity / allocated cost / credits / source:
Other recorded job costs / sources:
Actual total:
Difference against original budget:
Difference against revised budget:
Explanation by category / amount / evidence reference:
Unexplained amount / missing record:
Reviewer / decision / date:
Next action / responsible person / target date:
Customer report checked for internal information:
Use one explanation row per non-duplicated cost effect. Download the full editable review worksheet (.txt), which includes a reconciliation check and a separate customer-summary section.
Full editable worksheet
Preview the reconciliation and separate customer-summary fields
INTERNAL JOB COST DIFFERENCE REVIEW

Manual worksheet. Not a Fieldnox costing module or complete accounting ledger.
Use consistent cost policies and one stated currency. Keep internal rates,
supplier costs and review notes separate from customer-facing documents.
Repeat sections/rows as needed. Blank means unknown, not zero.

JOB AND BASIS
Job ID / site:
Reviewer / review date:
Currency:
Included cost categories / cost policy reference:
Exclusions (overhead / taxes / revenue / other):
Time basis: PERSON-HOURS (not elapsed visit duration)
Waiting / travel / breaks treatment:
Original scope / estimate reference / version / date:

BASELINES — do not replace the original
Original labor: person-hours x internal rate / amount:
Original materials / amount:
Original other included costs / amount:
A. Original job cost budget:
Approved change ID / date / scope / approval reference:
Customer price agreement reference (separate from internal cost allowance):
Added/reduced internal cost allowance / category / basis:
B. Net approved internal budget adjustments:
C. Revised job cost budget = A + B:

ACTUAL COST ENTRIES — repeat one row per unique cost allocation
Entry ID / date / category / task or change ID:
Worker, if labor / person-hours / internal cost rate / amount:
Material, if applicable / quantity USED / unit / allocated cost / amount:
Other included cost, if applicable / amount:
Return or credit adjustment / basis:
Source timesheet / receipt / stock issue / other reference:
Allocation check: Is this amount already included in another entry?
D. Total actual recorded job cost:

DIFFERENCES
E. Difference from original budget = D - A:
F. Difference from revised budget = D - C:

EXPLANATION ROW — repeat, with separate, non-duplicated cost effects
Explanation ID / affected entry IDs:
Category: original-scope estimate / changed scope / waiting / rework /
rate or purchase-price change / allocation correction / unexplained / other
Non-duplicated amount of E explained by this row:
Observed facts / time allocation / source cost reference:
Photo reference / location / stage / caption:
Supporting task note / approval reference:
Review decision / limits of evidence:

RECONCILIATION
G. Sum of explained amounts (signed values):
H. Remaining unexplained amount = E - G:
Do not force H to zero by inventing a reason.
Missing information / owner / target date:
Original and revised views retained? Yes / No
No duplicate time or material allocations? Yes / No / Unresolved
Consistent cost basis and currency? Yes / No / Unresolved

REVIEW ACTION
Decision / reviewer / date:
One estimating or operational action to test:
Responsible person / target date / follow-up review:

SEPARATE CUSTOMER SUMMARY — copy only supported client-relevant facts
Job / agreed scope:
Completed work / change references:
Relevant photos / checks actually performed / limits:
Open actions / responsible person / target date:
Acknowledgment obtained / exactly what was confirmed:
Commercial approval or price reference, where appropriate:

EXPORT REVIEW
Confirm no internal hourly cost, supplier cost, margin, staff discussion or
private review note appears in the intended customer report or shared link.
Review any customer charge separately against the applicable agreement and
authorization. Internal cost variance is not an automatic customer charge.
Turn the review into one practical change
Choose the action supported by the record. In this example, the next estimator should review the allowance for preparation on comparable doors. The office should also confirm access arrangements before a comparable visit. Added scope should remain separately identifiable.
These are actions to test, not evidence that a particular amount will be saved. Review the next comparable jobs before claiming an improvement.
Fieldnox is our product. The useful connection here is the field evidence and reporting record; this article does not claim that Fieldnox calculates job costs, tracks payroll or decides what is billable.
If your cost review stalls because the field record is unclear, use Fieldnox’s free report template to review the evidence behind the numbers and compare it with the record your team needs.